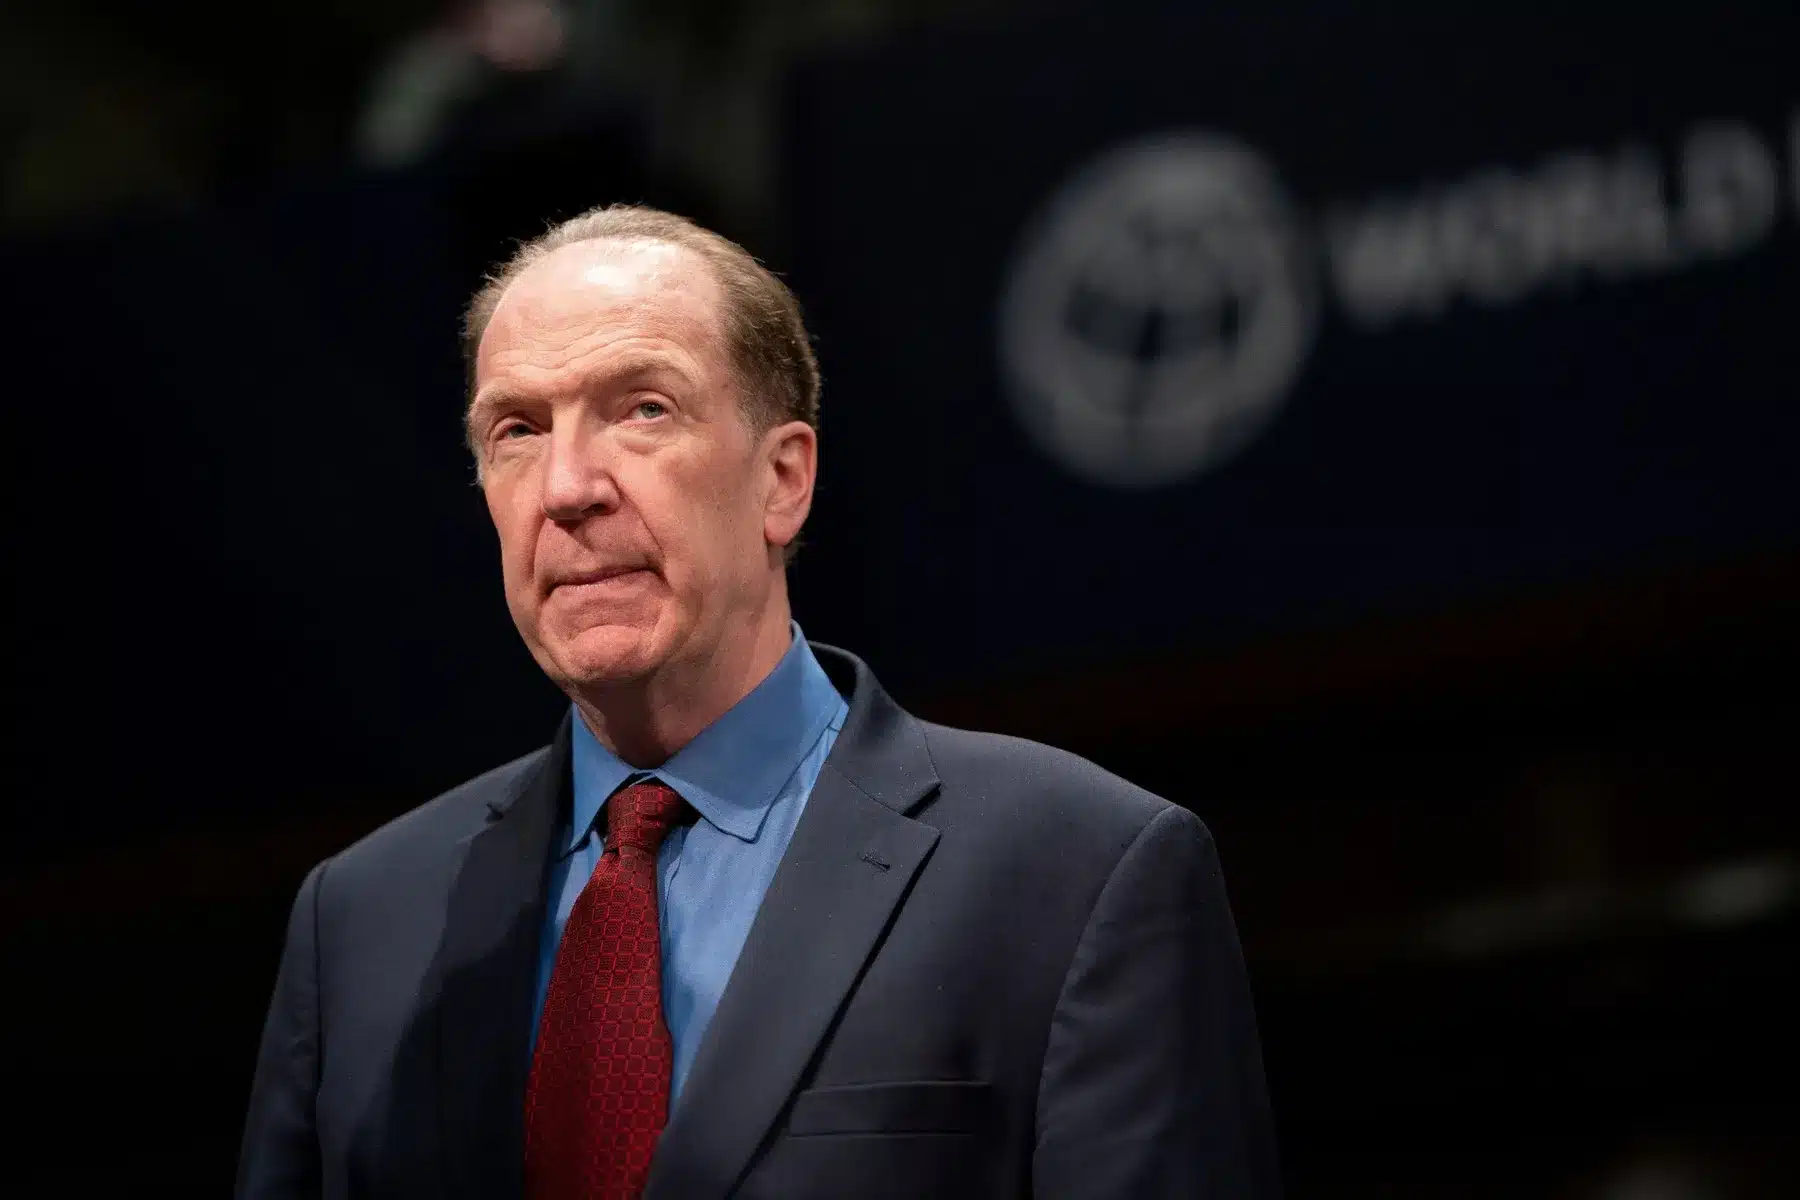
LAGOS, July 28 – Former World Bank President David Malpass has warned that Nigeria’s growing use of collateral-backed sovereign borrowing could complicate future debt restructuring efforts and undermine investor confidence if the country’s debt becomes unsustainable.
The concerns were outlined in a World Bank Policy Research Working Paper titled Public Debt and Central Banks, based on the Stanley Fischer Memorial Lecture delivered at the World Bank Group’s Annual Bank Conference on Development Economics.
Malpass argued that collateralised borrowing has become increasingly opaque across several developing economies, including Nigeria, creating greater complexity within sovereign debt markets.
According to Malpass, “Sophisticated new collateralized transactions, I saw ones in Angola, Nigeria, and Senegal are creating a new race toward seniority in the capital structure.”
He said the growing use of these financing structures could make future debt workouts significantly more difficult by giving certain creditors priority over others during restructuring processes.
Malpass also questioned the expanding use of guarantee products provided by multilateral development banks (MDBs), arguing that their effectiveness has yet to be tested during sovereign debt crises.
According to him, “This will add further complexity to restructurings as will the expansion of MDB guarantee products. Their sturdiness and value have not been tested in a restructuring context, and I am sceptical they are adding true value.”
Beyond Nigeria, Malpass criticised the broader international sovereign debt restructuring framework, arguing that limited transparency continues to hamper debt reconciliation efforts, particularly where borrowing agreements include confidentiality clauses or involve complex lending arrangements.
He said debt experts often remain “working in the dark” when assessing sovereign obligations, particularly in relation to some Chinese lending programmes and commercial financing agreements that contain non-disclosure provisions.
The former World Bank chief also highlighted Nigeria’s exchange rate regime as an area requiring further reform, arguing that currency stability is essential for stronger economic growth and rising household incomes.
He grouped Nigeria, Ethiopia and Egypt among countries where floating exchange rate systems and multiple exchange rate arrangements had, in his view, widened inequality by transferring wealth from lower-income earners to more privileged groups while exacerbating poverty.
According to the paper, Nigeria’s per capita income stands at approximately $1,500 per year, or about $4 per day, with median income remaining lower due to unequal income distribution.
Malpass argued that comprehensive currency reforms could substantially improve Nigeria’s economic performance.
According to him, “The upside from currency reform would be massive,” noting that Nigerians working abroad often earn “10 or 20 times as much” as those employed domestically.
He also revealed that during his tenure as World Bank President, he held several meetings with Nigeria’s previous administration and World Bank officials to identify reforms capable of accelerating economic growth.
Those discussions identified exchange rate unification and currency stabilisation, oil sector reforms, tax reforms, and agricultural liberalisation, particularly in rice production, as critical policy priorities.
Reflecting on the potential impact of those reforms, Malpass said, “These could transform Nigeria’s economy as much as China’s 1993 reforms launched its sustained 10% real growth rate.”
His comments come as Nigeria continues implementing economic reforms aimed at improving macroeconomic stability, strengthening public finances and restoring investor confidence while managing rising debt obligations.