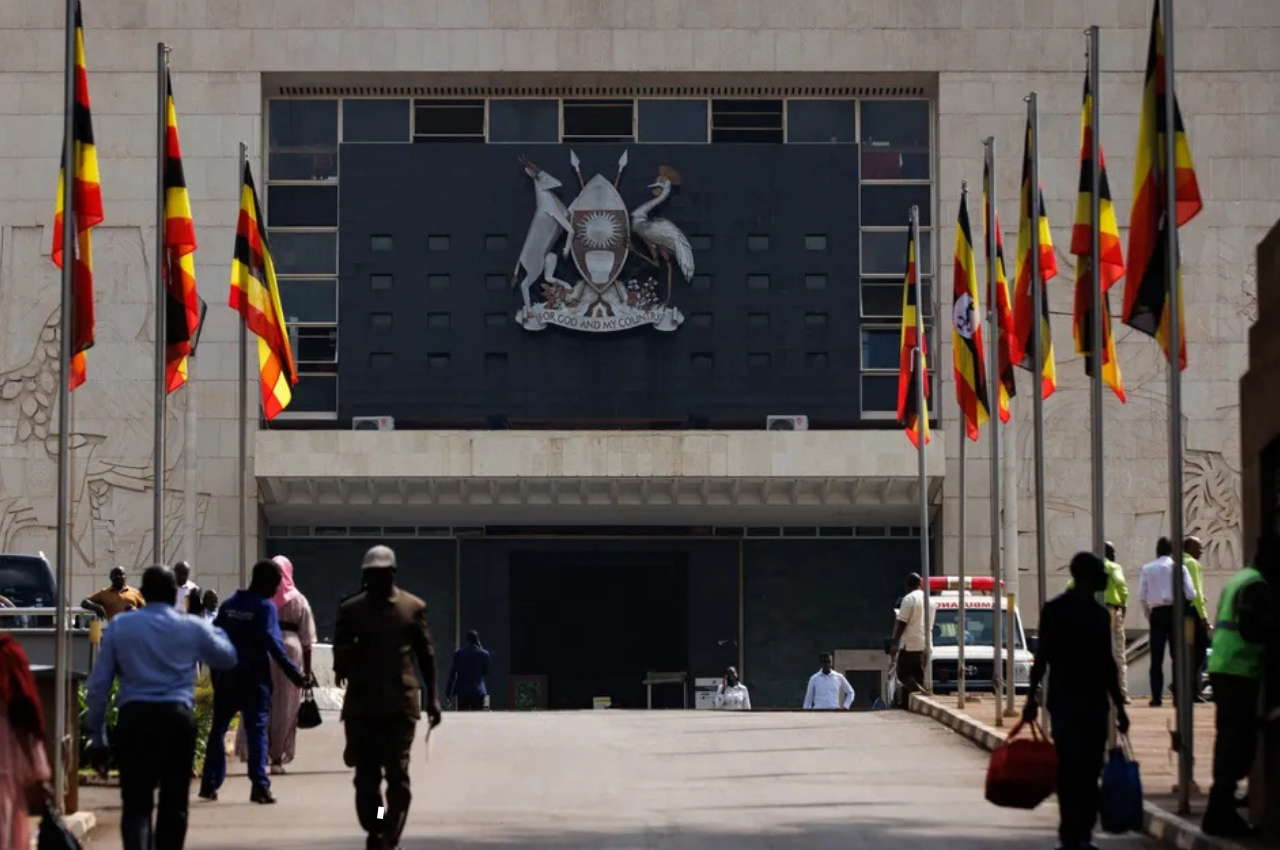
KAMPALA, Sept 20 – Uganda plans to reduce public spending by 6.2% in the 2027/28 financial year as the government seeks to scale back borrowing and manage rising debt-servicing costs ahead of the expected start of oil exports.
The Finance Ministry said the government plans to spend 79.2 trillion Ugandan shillings ($20.1 billion) in the 12 months beginning in July 2027, down from 84.4 trillion shillings in the previous financial year.
The ministry attributed the reduction to “reduced reliance on borrowing and external financing, and allocative efficiency,” although it did not provide details on the planned reduction in borrowing.
Uganda has been seeking to contain the growth of its public debt as higher debt-service costs increasingly constrain resources available for government priorities. The central bank has warned that rising repayment obligations are putting pressure on funding for sectors including health and education.
Despite the planned reduction in spending, the government expects economic growth to accelerate sharply. GDP growth in the 2027/28 financial year is projected at 9.1%, compared with a revised 7.6% forecast for the preceding period.
The Finance Ministry said the stronger outlook would be “driven by the onset of commercial production of oil and gas.”
Uganda expects to begin exporting crude oil early next year from oil fields in the western part of the country operated by France’s TotalEnergies, China’s CNOOC and the state-owned Uganda National Oil Company (UNOC).
The expected start of oil production represents a major shift in Uganda’s economic outlook, with the government anticipating new export revenues and broader activity linked to the petroleum sector.
Under the 2027/28 spending plan, government resources will be directed toward priority areas including agro-industrialisation, tourism and mineral development. Oil and gas development will also remain a central component of the government’s investment priorities.
The combination of tighter public spending and expected oil production reflects Uganda’s effort to balance fiscal pressures with investment in sectors viewed as important to future economic growth.