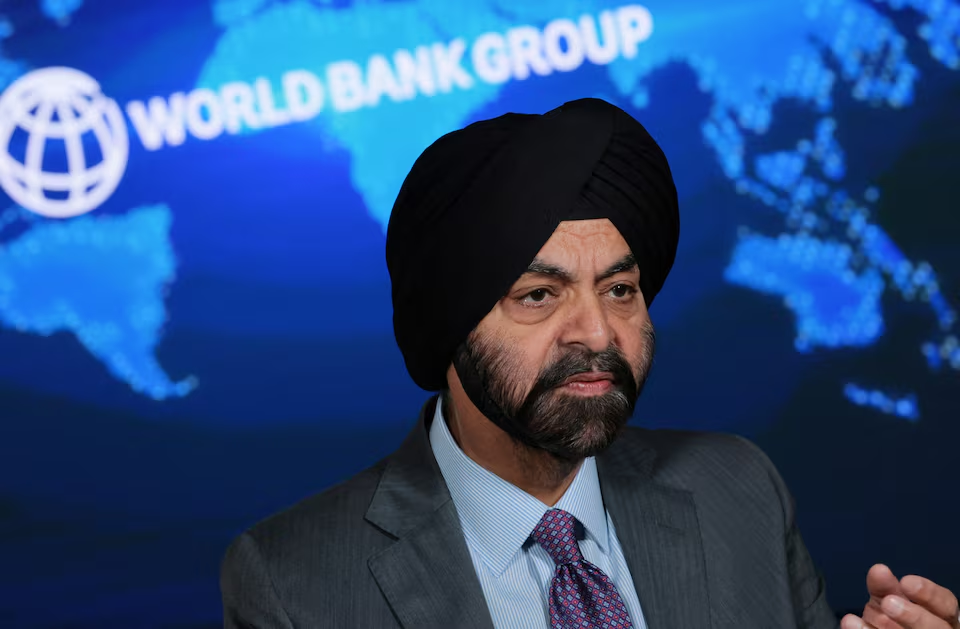
NAIROBI, Nov 4 – The World Bank has warned that Kenya’s expanding range of taxes and government levies could increase corruption risks for businesses, as multiple charges and administrative processes create additional opportunities for bribery demands.
In its November 2026 Kenya Economic Update, the Washington-based lender identified several charges imposed on businesses, including the Affordable Housing Levy, Railway Development Levy and Import Declaration Fee. It also highlighted increases in road and petroleum levies, warning that the accumulation of charges could complicate tax compliance and create greater scope for irregular practices during tax administration.
“The pile-up of charges raises the risk of bribe demands,” the World Bank warned, pointing to the corruption risks associated with multiple charges and the administrative processes involved in paying them.
The concerns come as the Kenyan government continues to face difficulties meeting its revenue collection targets. Tax revenue currently stands at 12.8% of gross domestic product, below the government’s target of 13.3%.
Value Added Tax (VAT) and income tax account for 79.4% of total tax revenue, making their performance central to the government’s efforts to strengthen public finances.
The World Bank attributed part of the VAT collection shortfall to the government’s April 2026 decision to reduce VAT on fuel from 16% to 8%. Following the reduction, VAT collections were 6.4% below target.
“VAT collections were 6.4 per cent below target,” the report stated, highlighting the revenue implications of the lower tax rate on petroleum products.
The findings underline the challenge facing Kenya’s fiscal authorities as they seek to increase government revenue while managing the cumulative tax burden on businesses. The introduction and maintenance of multiple charges can raise compliance costs, while weaknesses in their administration may undermine transparency and create opportunities for corruption.
Beyond changes to tax policy, the World Bank called for improvements in the administration of taxes and government fees. Its recommendations include more transparent procedures, reduced discretion by public officials and stronger safeguards against irregular practices.
The lender also proposed greater use of digital systems to make tax assessments more transparent and improve accountability. It recommended allowing taxpayers to track the status of refunds and audits, alongside mechanisms for escalating unresolved disputes.
The report suggests that strengthening Kenya’s revenue mobilisation will require more than expanding the tax base or introducing additional levies. Improving administrative efficiency, reducing opportunities for bribery and building public confidence in the tax system will also be important to sustaining compliance and meeting government revenue targets.