NAIROBI, Sept 29 – Renaissance Capital has proposed a Global Depositary Receipt (GDR) structure that could give investors in Kenya and other East African markets a local route to participate in Dangote Refinery’s planned initial public offering in Nigeria.
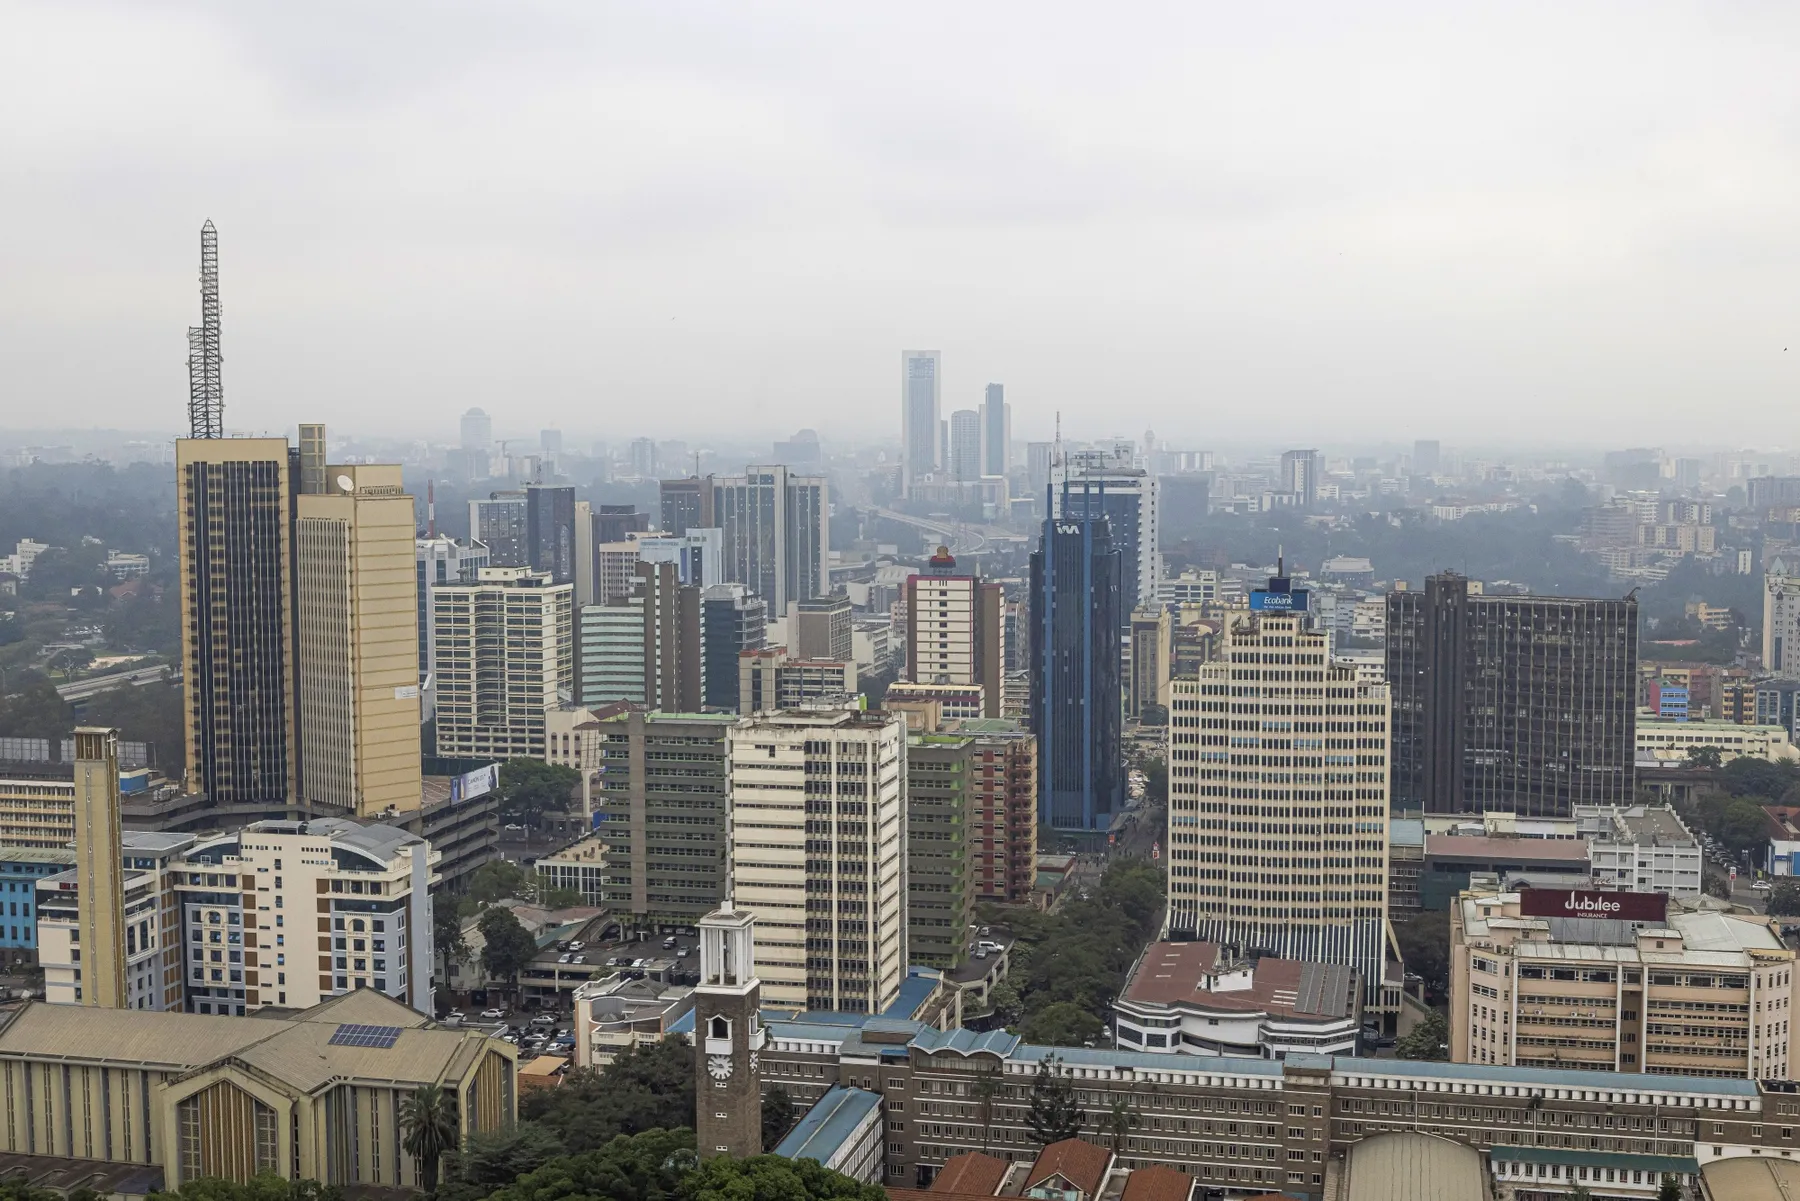
The proposed arrangement would link Dangote Refinery’s Nigerian ordinary shares with GDRs that could be made available through the Nairobi Securities Exchange (NSE), subject to the required regulatory approvals and implementation of the structure.
The proposal does not represent a listing of Dangote Refinery on the NSE. Instead, it is designed to provide Kenyan investors with access to the Nigerian share offer through Kenya’s existing capital-market infrastructure.
Stanley Kariuki, CEO of Renaissance Capital Kenya, said the initiative was developed around the question of how investors in Kenya and the wider East African region could participate in the transaction.
“Our question at Renaissance Capital was simple: how do we enable Kenya and East African investors to participate in this landmark opportunity?”
Kariuki said developing the structure required cooperation among several financial-market institutions.
“It brought together a strong consortium led by Renaissance Capital Kenya and Renaissance Capital Nigeria, working alongside Stanbic as the custodian, Image Registrar, GNA Advocates and Newmark.”
He also acknowledged the involvement of the Nairobi Securities Exchange and Kenya’s Capital Markets Authority in developing the proposed framework.
“I would like to take this opportunity to thank the Nairobi Securities Exchange, led by the CEO, and the Capital Markets Authority for their support and commitment to ensuring that our local investors have the opportunity to participate.”
How the proposed GDR structure would work
Under the proposed arrangement, Dangote Refinery’s ordinary shares would remain held in Nigeria rather than being transferred to Kenya.
The underlying shares would be deposited with a custodian in Lagos. Once the deposit had been confirmed, corresponding GDRs could be issued through the Kenyan depositary structure.
If approved and admitted for trading, the GDRs would provide Kenyan investors with an instrument linked to the Nigerian shares while allowing transactions to take place through Kenya’s capital-market infrastructure.
The proposed GDRs would settle through the Central Depository and Settlement Corporation in Kenyan shillings, creating a local-market mechanism for investors seeking exposure to the Nigerian IPO.
Kariuki said the structure had to be developed within a limited timeframe because of the IPO window.
“Of course, creating this solution came with a number of challenges. First, time. The IPO window is limited, and we had to develop and execute a solution within a very tight timeline.”
Transparency around pricing, costs and investor treatment was another consideration.
“Secondly, transparency. Any product we introduced had to provide clarity on pricing, costs, and the treatment of investors both during and after the IPO.”
The structure would also address the currency differences between the Nigerian share offer and investors operating in Kenya.
“Third, currency and foreign exchange consideration. This is fundamentally a Kenyan shilling denominated investment solution, providing access to an offshore opportunity.”
Proposed participants in the transaction
Renaissance Capital Africa would act as issuer, lead transaction adviser and sponsoring broker under the proposed structure. Its responsibilities would include advising on the GDR programme, including the ratio, size and pricing, while coordinating the prospectus, valuation, regulatory submissions and investor distribution.
The Nairobi Securities Exchange would serve as project coordinator, with responsibilities covering transaction documentation, the proposed timetable, issuance and cancellation procedures, and readiness for the relevant regulatory processes.
Stanbic Bank would act as the receiving bank and custodian/depositary, including holding the underlying Nigerian shares in segregated custody and facilitating the issuance and cancellation of GDRs.
GBA Advocates LLP would provide legal services, while participating brokers would be responsible for areas including investor eligibility, know-your-customer and anti-money-laundering checks, suitability, allocation and distribution.
A registrar would maintain the register of GDR holders, process transfers and payments, and reconcile records with the depositary and custodian.
Linking Nigerian shares with East African capital
The proposed structure would effectively create a connection between two capital markets.
In Nigeria, the underlying Dangote Refinery shares would remain deposited with a local custodian and continue to be linked to the Nigerian market. In Kenya, the corresponding GDRs could provide an instrument for investors to access that exposure through the NSE and settle transactions in Kenyan shillings.
The proposed process would begin with the Nigerian issuer depositing ordinary shares with the custodian in Lagos. Following confirmation of the deposit, the Kenyan depositary would issue GDRs against those shares.
If the necessary approvals are secured, the GDRs could then be admitted to the NSE and made available to eligible investors through licensed Kenyan brokers.
Kariuki said the initiative reflected a broader objective of connecting African capital with investment opportunities elsewhere on the continent.
“The solution we are proposing, a GDR structure, demonstrates what can be achieved when the capital markets institutions, regulators, custodians, advisors, investment banks come together around a common objective.”
He said the proposed framework could have implications beyond the Dangote Refinery transaction by demonstrating how African capital markets could become more interconnected.
“It is more than one transaction. It is about connecting African capital to Africa opportunities. It is about making our capital markets more integrated.”
The proposal comes as financial-market institutions explore mechanisms that could allow investors outside Nigeria to participate more easily in Dangote Refinery’s share offering. If implemented, the GDR structure would provide Kenyan investors with a locally accessible instrument while maintaining the underlying equity exposure in Nigeria.