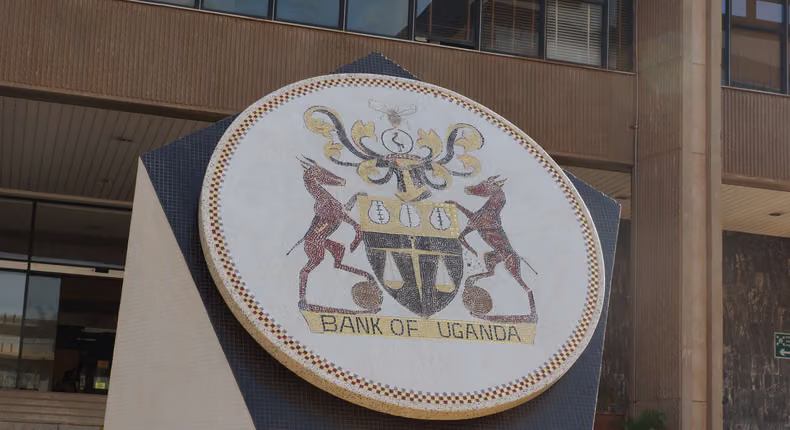
KAMPALA, Oct 13 – Uganda’s foreign exchange reserves increased 56% year-on-year to $6.7 billion in the 12 months to June, strengthening the country’s external financial position as the central bank prepares to expand its gold purchasing programme.
The reserves rose from $4.3 billion a year earlier, according to a report released by the Bank of Uganda on Monday. The central bank said the increase had reinforced confidence in the country’s macroeconomic position and its ability to withstand external shocks.
“These gains reinforced confidence in Uganda’s macroeconomic position and external-sector resilience,” the bank said.
Despite the increase, reserves remain below the central bank’s preferred import-cover threshold. The $6.7 billion stock is equivalent to approximately 3.7 months of future imports, compared with the bank’s target of four months.
Central Bank Expands Gold Reserve Strategy
The Bank of Uganda plans to continue its gold purchasing programme during the 2026/27 financial year, which runs through June 2027, as part of efforts to diversify its reserve holdings.
Gold purchases can help reduce reliance on conventional foreign currency assets and provide an additional store of value during periods of global financial uncertainty. The programme forms part of the central bank’s broader reserve-management strategy.
Reserves and Pressure on the Shilling
The increase in reserves comes as the Ugandan shilling has weakened sharply in recent weeks, falling through successive record lows.
A larger reserve buffer can strengthen a country’s capacity to meet external payment obligations and help manage temporary foreign exchange pressures. However, the increase does not necessarily translate into a commitment to defend a particular exchange rate.
The Bank of Uganda has said it does not target a specific level for the shilling and does not intend to intervene simply to reverse currency movements. Instead, its approach is focused on smoothing excessive volatility in the foreign exchange market.
Uganda’s reserve position has therefore improved considerably, although the shilling’s recent depreciation and the gap between current import cover and the central bank’s target remain important indicators to watch.